


Page 528 - JoFA_2022
P. 528
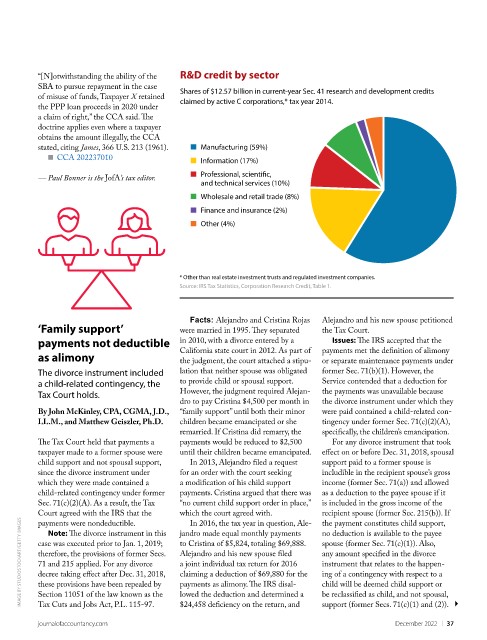
R&D credit by sector
          “[N]otwithstanding the ability of the
          SBA to pursue repayment in the case
                                            Shares of $12.57 billion in current-year Sec. 41 research and development credits
          of misuse of funds, Taxpayer X retained
                                            claimed by active C corporations,* tax year 2014.
          the PPP loan proceeds in 2020 under
          a claim of right,” the CCA said. The
          doctrine applies even where a taxpayer
          obtains the amount illegally, the CCA
                                                         ing (59%)
                                                  anufac
                                                 M
                                                       tur
          stated, citing James, 366 U.S. 213 (1961).   ■   Manufacturing (59%)
            ■   CCA 202237010                 ■   Information (17%)
                                                 nf
                                                 I
                                                      tion (17%)
                                                    ma
                                                  or
                                                    essional
                                                 P
                                                              tific
                                                                 ,
                                              ■   Professional, scientific,
                                                  of
                                                 r
                                                          , scien
          — Paul Bonner is the JofA’s tax editor.
                                                             vic
                                                               es (10%)
                                                 and technical services (10%)
                                                 and t
                                                    echnical ser
                                              ■   Wholesale and retail trade (8%)
                                                  holesale and r
                                                 W
                                                                 ade (8%)
                                                            etail tr
                                                 inanc
                                              ■   Finance and insurance (2%)
                                                              anc
                                                                e (2%)
                                                     e and insur
                                                 F
                                                 O
                                              ■   Other (4%)
                                                  ther (4%)
                                            * Other than real estate investment trusts and regulated investment companies.
                                            Source: IRS Tax Statistics, Corporation Research Credit, Table 1.
                                              Facts: Alejandro and Cristina Rojas   Alejandro and his new spouse petitioned
          ‘Family support’                  were married in 1995. They separated   the Tax Court.
          payments not deductible           in 2010, with a divorce entered by a   Issues: The IRS accepted that the
          as alimony                        California state court in 2012. As part of   payments met the definition of alimony
                                                                             or separate maintenance payments under
                                            the judgment, the court attached a stipu-
          The divorce instrument included   lation that neither spouse was obligated   former Sec. 71(b)(1). However, the
          a child-related contingency, the   to provide child or spousal support.   Service contended that a deduction for
          Tax Court holds.                  However, the judgment required Alejan-  the payments was unavailable because
                                            dro to pay Cristina $4,500 per month in   the divorce instrument under which they
          By John McKinley, CPA, CGMA, J.D.,   “family support” until both their minor   were paid contained a child-related con-
          LL.M., and Matthew Geiszler, Ph.D.   children became emancipated or she   tingency under former Sec. 71(c)(2)(A),
                                            remarried. If Cristina did remarry, the   specifically, the children’s emancipation.
          The Tax Court held that payments a   payments would be reduced to $2,500   For any divorce instrument that took
          taxpayer made to a former spouse were   until their children became emancipated.  effect on or before Dec. 31, 2018, spousal
          child support and not spousal support,   In 2013, Alejandro filed a request   support paid to a former spouse is
          since the divorce instrument under   for an order with the court seeking   includible in the recipient spouse’s gross
          which they were made contained a   a modification of his child support   income (former Sec. 71(a)) and allowed
          child-related contingency under former   payments. Cristina argued that there was   as a deduction to the payee spouse if it
          Sec. 71(c)(2)(A). As a result, the Tax   “no current child support order in place,”   is included in the gross income of the
          Court agreed with the IRS that the   which the court agreed with.  recipient spouse (former Sec. 215(b)). If
      IMAGE BY STUDIOSTOCKART/GETTY IMAGES  case was executed prior to Jan. 1, 2019;   to Cristina of $5,824, totaling $69,888.   spouse (former Sec. 71(c)(1)). Also,
                                                                             the payment constitutes child support,
                                              In 2016, the tax year in question, Ale-
          payments were nondeductible.
            Note: The divorce instrument in this
                                            jandro made equal monthly payments
                                                                             no deduction is available to the payee
          therefore, the provisions of former Secs.
                                                                             any amount specified in the divorce
                                            Alejandro and his new spouse filed
          71 and 215 applied. For any divorce
                                                                             instrument that relates to the happen-
                                            a joint individual tax return for 2016
                                            claiming a deduction of $69,880 for the
          decree taking effect after Dec. 31, 2018,
                                                                             ing of a contingency with respect to a
                                                                             child will be deemed child support or
          these provisions have been repealed by
                                            payments as alimony. The IRS disal-
          Section 11051 of the law known as the
                                                                             support (former Secs. 71(c)(1) and (2)).
                                            $24,458 deficiency on the return, and
          Tax Cuts and Jobs Act, P.L. 115-97.
                                                                                               December 2022    |   37
          journalofaccountancy.com          lowed the deduction and determined a   be reclassified as child, and not spousal,

